Buy Property in Dubai with Union Square House
Buy property in Dubai with a RERA-licensed advisor beside you from the first shortlist to the day you collect your title deed. Whether you live in the UAE or overseas, buying a home or an investment, ready or off-plan, we check the price against recent sales, negotiate on your behalf and handle the contracts, NOC and transfer, so you buy with confidence.
Free consultation
Talk to a buying advisor
- 200+Awards From Top Developers
- 150+Team Members
- $10BTransaction value
- 100+Licensed Agents
- 4Offices in UAE
- 20+Nationalities
Properties for Sale
A selection of ready and off-plan homes across Dubai's most popular communities, each listed with a valid DLD permit and a named advisor you can contact directly.
 Ready
AED 2,400,000
Nobles Tower, Business Bay
2 beds3 baths1,259 sq ft
 Off-plan
AED 3,230,000
The Yards Plaza Building D, City of Arabia
1 bed1 bath1,455 sq ft
 Ready
AED 2,950,000
Royal Regency, Business Bay
2 beds3 baths1,320 sq ft
 Ready
AED 100,000,000
La Mer South Island, Jumeirah
6 beds7 baths12,851 sq ft
 Off-plan
AED 4,225,000
The Yards Plaza Building D, City of Arabia
1 bed1 bath1,911 sq ft
 Ready
AED 1,760,000
Royal Regency, Business Bay
1 bed2 baths868 sq ft
 Ready
AED 1,100,000
Belgravia Heights 1, Jumeirah Village Circle
1 bed2 baths832 sq ft
 Ready
AED 50,500,000
Sobha Hartland, Mohammed Bin Rashid City
4 beds5 baths6,018 sq ft
Browse Property by Budget, Area and Type
Freehold Areas: Where Foreigners Can Buy
In Dubai's freehold areas, buyers of any nationality can own property outright, with the title deed registered in their name at the Dubai Land Department. Outside these areas, ownership is usually limited to UAE and GCC nationals or offered on a long leasehold.
Read more: Emerging freehold communities to watch in 2026 · Sheikh Zayed Road goes freehold
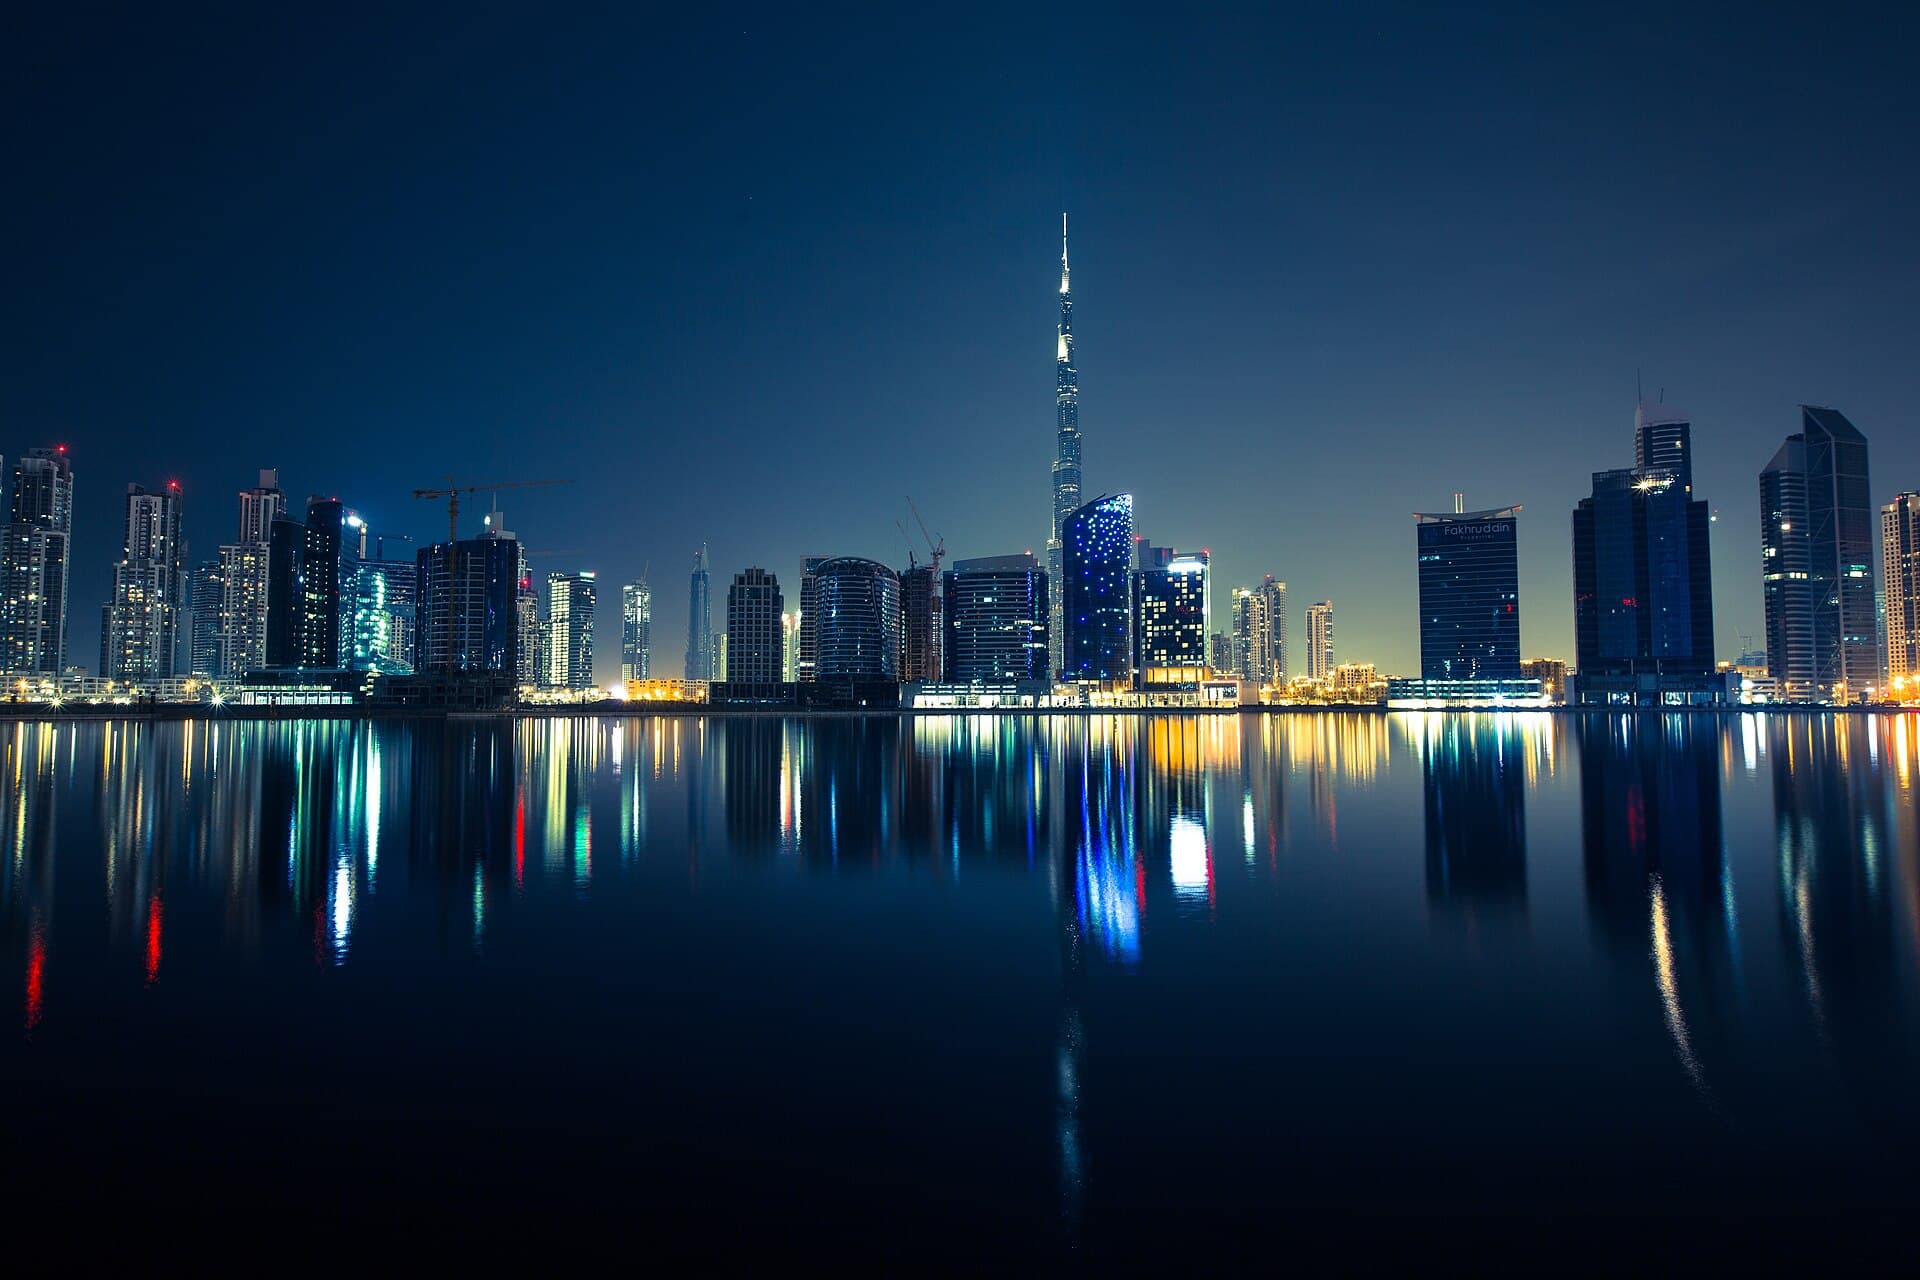

- Downtown DubaiApartments near Burj Khalifa and Dubai Mall
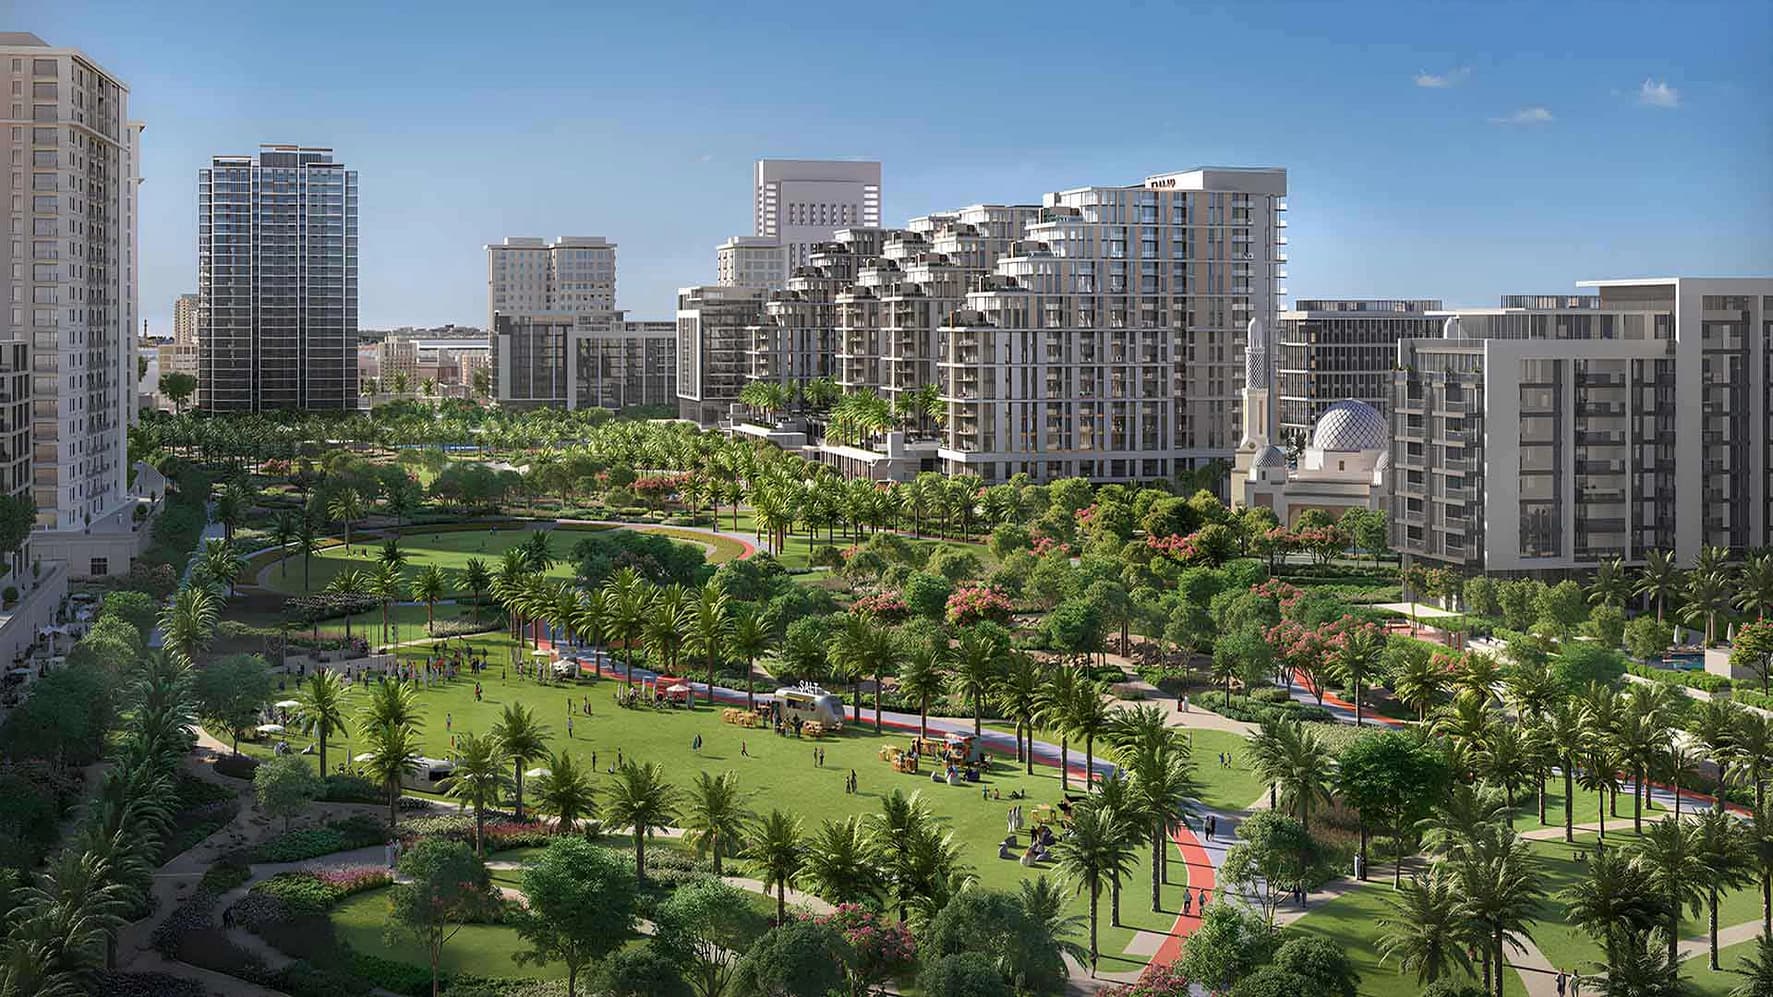
- Dubai Hills EstateVillas, townhouses and a central park
- Dubai MarinaWaterfront apartments, strong rental demand
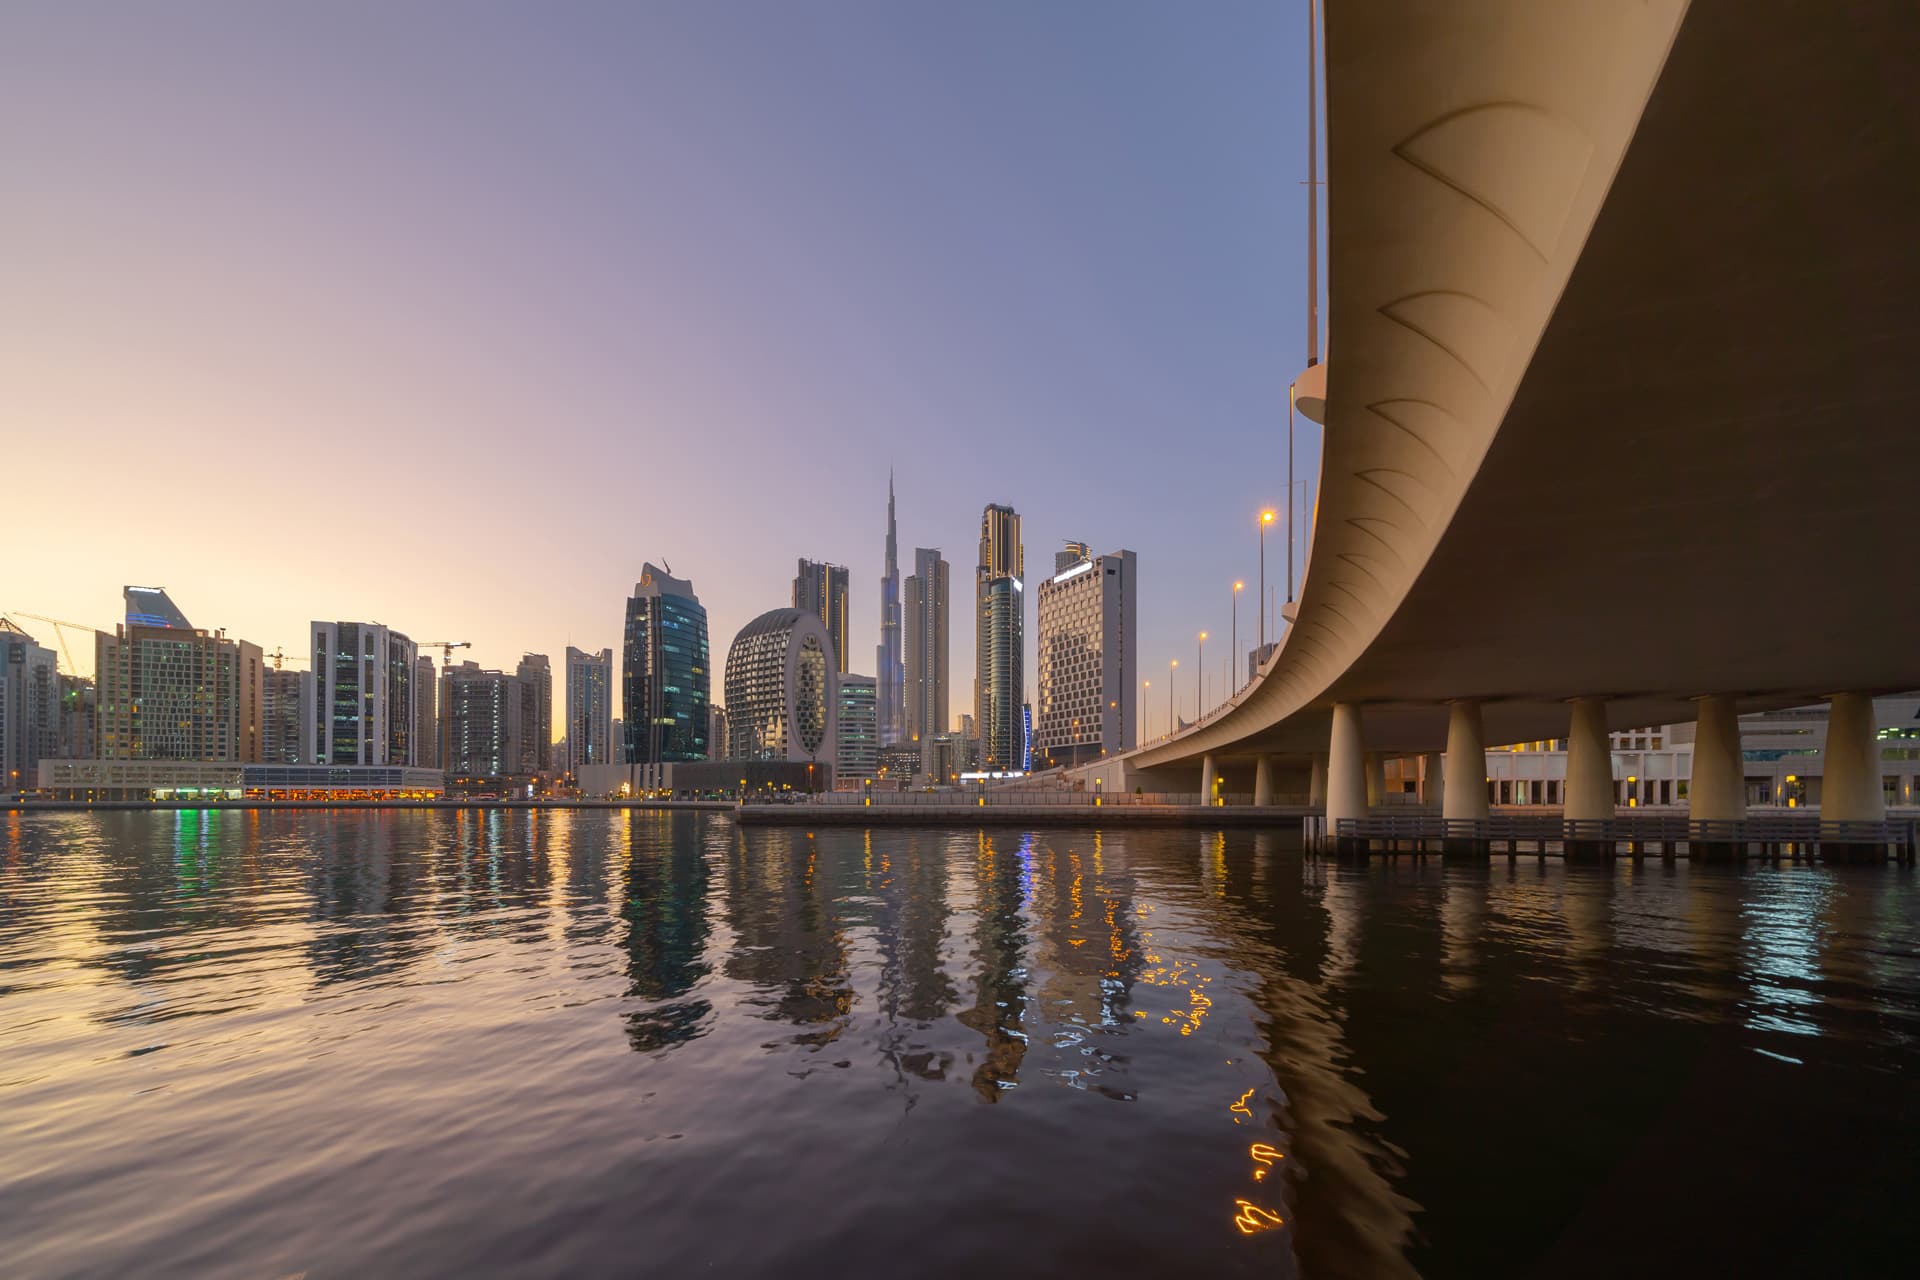
- Palm JumeirahBeachfront villas and branded residences
- Business BayCanal-side apartments close to Downtown
- Jumeirah Village CirclePopular with first-time buyers and investors
- Arabian RanchesEstablished family villa community
- Town SquareTownhouses and apartments at entry prices
- MeydanNew launches and villas near the city
- Dubai SouthNear Al Maktoum Airport and Expo City
Who We Help Buy Property in Dubai
First-time buyers
Buying for the first time in Dubai? We explain every fee and step before you commit, shortlist homes that fit your budget and stay with you through to the keys.
Investors
We compare rental yield, service charges and resale demand across communities, and show you the numbers behind every recommendation so you can judge the return yourself.
Overseas buyers
Buy from London, Mumbai or anywhere else. We arrange video viewings, guide you through power of attorney and coordinate the transfer if you can't be in Dubai.
Luxury buyers
Private viewings of prime villas, penthouses and branded residences, including off-market homes, with discreet handling from first call to completion.
Documents You Need to Buy Property in Dubai
Have these ready before you make an offer. It keeps the sale moving and avoids delays at transfer.
0 of 5 readyTick each document you already have.
0 of 5 readyTick each document you already have.
UAE residents
Overseas buyers
Buying Property in Dubai from Abroad
You don't need to live in Dubai, or even visit, to buy property here. Non-residents can buy in Dubai's freehold areas, and many of our clients complete their purchase from overseas, with their advisor handling viewings, paperwork and transfer, and a power of attorney where needed.
Video viewings
Live video walkthroughs of every shortlisted home at a time that suits your time zone, with honest notes on condition, views, noise and the building.
Power of attorney
If you can't attend the transfer, a person you trust can sign for you. We explain how to prepare the power of attorney and have it notarised and attested for use in Dubai.
Paying from overseas
You can send funds by international bank transfer at each stage. We tell you exactly where each payment goes, whether to the seller, the DLD or the project escrow account for off-plan, and you get a receipt every time.
Remote signing
Many contracts can be signed electronically, and the Dubai Land Department issues title deeds in digital form, so you can complete your purchase without flying in.
Ready or Off-Plan: Which Suits You?
Both can be a good way to buy property in Dubai. The right choice depends on when you want to move in or earn rent, how you prefer to pay, and how much risk you are comfortable with. Here is how they compare.
| Ready property | Off-plan property | |
|---|---|---|
| Best for | Ready property: Buyers who want to move in soon, or investors who want rental income now | |
| How you pay | Ready property: A deposit when you sign Form F, then the balance in cash or with a mortgage at transfer | |
| Move in or rent out | Ready property: Straight after transfer, unless the home is already rented to a tenant | |
| Price | Ready property: Market price, based on recent sales, with room to negotiate | |
| Mortgage | Ready property: Widely available from UAE banks | |
| Main risk | Ready property: Condition of the property, service charges and any existing tenancy | |
| How your money is protected | Ready property: The deposit is held as agreed in Form F, and the balance is paid at a DLD trustee office on the day ownership transfers |
Off-plan vs ready property: which is better → · Browse off-plan projects → · Browse ready homes →
Not sure which is right for you? Talk to an advisor →
How Buying Works with USH
- Requirement mappingWe agree your budget, areas, property type and timeline, and whether ready or off-plan suits you.
- Shortlist and viewingsYou get a shortlist with recent comparable prices, then view the homes that fit, in person or by video.
- Offer and negotiationWe plan the offer, negotiate price and terms, and advise you at every counter-offer.
- Sale agreement (Form F)Buyer and seller sign the DLD sale contract and the agreed deposit is arranged.
- NOC and financeWe coordinate the developer's NOC and, if you use a mortgage, the bank valuation and approval.
- Transfer and keysOwnership transfers at a DLD trustee office, your title deed is issued and you get the keys.
Buying off-plan? The sale is registered with the DLD (Oqood) and payments go to the project's escrow account.
Off-plan handover guide →What It Costs to Buy Property in Dubai
Plan for roughly 6–7% on top of the purchase price for a cash purchase, more if you take a mortgage. Here is where that money goes.
| Fee | Typical amount | Paid by |
|---|---|---|
| DLD transfer fee4% of the purchase price | 4% of the purchase price | Buyer |
| Trustee office feeAED 2,000–4,000 + VAT, depending on price | AED 2,000–4,000 + VAT, depending on price | Buyer |
| Agency commissionUsually 2% + VAT | Usually 2% + VAT | Buyer |
| Mortgage registration0.25% of the loan + admin fee | 0.25% of the loan + admin fee | Buyer (if financed) |
| Developer NOCAED 500–5,000, varies by developer | AED 500–5,000, varies by developer | Seller (often) |
| Title deed issueSmall admin fee | Small admin fee | Buyer |
Source: Dubai Land Department.
Example
AED 2M ready apartment, cash
- Purchase price
- AED 2,000,000
- DLD transfer fee (4%)
- AED 80,000
- Agency commission (2% + VAT)
- AED 42,000
- Trustee office fee + VAT
- AED 4,200
- Title deed and admin
- AED 600
- Total cash needed
- AED 2,126,800
Mortgages for Buyers in Dubai
Both UAE residents and non-residents can get a mortgage to buy property in Dubai. The main differences are the deposit you need, the documents the bank asks for, and whether the property is ready or off-plan. Here's what to expect before you apply.
Advisor tip: get mortgage pre-approval before you make an offer. Sellers take your offer more seriously, and you know your real budget, including the extra 6–7% for fees. Mortgage calculator → · Off-plan mortgage guide →
| UAE residents | Overseas buyers | |
|---|---|---|
| Typical minimum deposit | 20% for expat residents buying a first home up to AED 5M; 30% above AED 5M. UAE nationals from 15%. | Usually 40–50%, depending on the bank and your income |
| Documents | Passport, Emirates ID and visa, salary certificate or proof of business income, and recent bank statements (usually 6 months) | Passport, proof of address, proof of income (payslips or audited accounts), 6–12 months' bank statements, and a credit report from your home country |
| Pre-approval | Recommended before you make an offer. It confirms your budget. | Recommended, and can usually be arranged remotely |
| Off-plan | Off-plan loans are capped at 50% of the price, so expect to fund at least half yourself. Most banks lend only close to handover. | Limited; most overseas buyers use the developer's payment plan |
| Extra costs | Mortgage registration at the DLD (0.25% of the loan plus an admin fee), a bank valuation fee and an arrangement fee, set by each bank | Same as residents: DLD mortgage registration, valuation and arrangement fees |
What You Get When You Buy with USH
Our property buying service gives you one advisor from first call to keys, backed by a transaction team that handles the checks, contracts and transfer for you.
- 01
Before you buy
- A shortlist with recent comparable sale prices
- Title deed and seller identity checks
- Developer and escrow checks for off-plan
- 02
The deal
- Offer strategy and negotiation on your behalf
- Mortgage coordination with banks
- Form F, NOC and contract handling
- 03
Transfer
- A transaction manager on transfer day
- 04
After you buy
- Help with snagging, utilities and move-in
- Leasing or property management after you buy
- Advice on resale or rental value when you need it
Why Buyers Choose Union Square House
Dubai's developers rank the brokers who sell their homes on results, and Union Square House has been on those lists every year since 2014, including Emaar, Nakheel, Binghatti and Nshama. For buyers, that means an advisor with direct access to developers and a record you can check. Why we're a top Dubai broker →
Emaar ranked us No. 2 for sales from 2021 to 2025, and Binghatti named us its No. 1 broker for H1 2026. Strong developer relationships mean earlier access to launches and better-informed advice on every project.
Each advisor specialises in specific communities, so they know the buildings, layouts, service charges and recent sale prices. You get advice based on local detail, not general market averages.
We regularly host open houses where you can view several homes in one visit, without booking separate appointments. See what's coming up on our open houses page.
Our Investment Playbook, ROI calculator and purchase cost calculator show the numbers behind our advice, from rental yields to total buying costs, so you can test every recommendation yourself.
EmaarNo. 4 Agency of Emaar2026
- Awards from 28 developers and industry bodies
- 200+
- For Emaar sales, 2021 to 2025
- No. 2
Advice from Our Buying Advisors
Short answers to the questions buyers ask us most.
Choose a question
You asked: Is now a good time to buy property in Dubai?
“The right time depends on your plans, budget and how long you intend to hold the property. Compare recent transactions and current asking prices in the specific area, and make sure the total costs work for you before deciding.”
You asked: Should I buy ready or off-plan in Dubai Hills Estate?
“If you need to move in within a year, buy ready. Off-plan suits buyers who can wait and want to spread payments, but compare the launch price with ready resale prices in the same cluster first.”
You asked: How much can I negotiate on the asking price?
“It depends on how long the home has been listed and how many similar units are for sale. We show you recent sales in the building so your offer is based on evidence, not a guess.”
You asked: Where should I buy my first home under AED 1M?
“Look at service charges as closely as the price. Two apartments at the same price can differ by thousands a year in charges, which affects your monthly cost and resale value.”
You asked: What mistakes do buyers make most often in Dubai?
“Common mistakes include budgeting only for the purchase price, skipping checks on the title deed or developer, and relying on projected returns without checking the costs. Review the documents, fees and comparable sales before committing.”
What Buyers Say
“Zoya guided me with valuable market insights and helped identify the right property to match my requirements. Thanks to her personalized approach, efficiency, and genuine client care, we successfully closed a great deal at Binghatti Lavender.”
Buyer Guides and Tools
Everything you need to plan, finance and complete your purchase in Dubai.
Decide
Where to buy

Finance
Buying Property in Dubai: FAQs
Still have a question? Ask a buying advisor →
Yes. Buyers of any nationality can own property outright in Dubai's freehold areas, such as Downtown Dubai, Dubai Marina, Dubai Hills Estate and Palm Jumeirah. You don't need a UAE residence visa to buy.
Budget around 6–7% on top of the price for a cash purchase. The largest cost is the 4% DLD transfer fee, followed by agency commission and trustee fees. Use our property purchase calculator for your exact figure.
Yes, several UAE banks lend to non-residents, usually with a larger deposit than residents and extra income documents. Getting pre-approval first tells you your real budget.
A cash purchase of a ready property often completes within a few weeks of signing Form F. With a mortgage, allow extra time for the bank valuation and approval. Your advisor gives you a timeline at the offer stage.
Off-plan sales are regulated: the project must be registered with RERA, your purchase is registered with the DLD (Oqood), and payments go into the project's escrow account. Checking the developer's track record still matters.
Property investors can qualify for a UAE Golden Visa above a minimum property value. Your advisor can confirm the current threshold and conditions for the property you are considering.
There is no annual property tax in Dubai, and individuals pay no income tax on rent or capital gains tax when they sell a home. Buying a residential property also doesn’t attract VAT on the price: the first sale of a new home is zero-rated and resales are exempt. VAT at 5% does apply to commercial property and to services such as agency commission. The main government cost when you buy is the one-off 4% Dubai Land Department transfer fee. Companies and commercial property may be treated differently, so take tax advice if you’re buying through a business. See what it costs to buy property in Dubai.
The main yearly cost is the service charge, which pays for maintenance, security and shared facilities in your building or community. It’s charged per square foot and varies widely between developments, so always check it before you buy. You’ll also pay DEWA for water and electricity, which includes a municipality housing fee, and some buildings charge separately for district cooling. Most owners also budget for home insurance and routine maintenance. If you rent the property out, add a property management fee if you use a manager, and Ejari registration for each new tenancy. Your advisor can give you the service charge for any property before you make an offer.
Rental yields in Dubai vary by community, property type and price, and are generally higher for apartments than for villas. Gross yields commonly fall between 5% and 8%, but your actual return depends on the purchase price, service charges, vacancy periods and whether you use a property manager. Your net yield, after these costs, is the figure that matters. We work out both gross and net yields for any property you’re considering, using recent rents in the same building. Read our guide to the areas with the highest rental yields in 2026 or try our ROI calculator.
Yes, you can rent your property for short stays, but you need a holiday home permit from Dubai’s Department of Economy and Tourism, and the property must meet its standards for furnishing and safety. Some buildings and communities don’t allow short-term letting, so check the building rules before you buy if this is your plan. You can manage the property yourself or use a licensed holiday home operator, who handles the permit, guests and cleaning for a fee. Holiday lets can earn more than long-term rentals, but income varies with the season. Read Dubai’s short-term rental boom.
Yes, many buyers sell off-plan properties before completion. Most developers only allow a resale once you’ve paid a set share of the price, often around 30–40%. Once you have the developer’s NOC, the sale is registered with the Dubai Land Department, and the new buyer takes over the remaining payment plan. Fees apply, including the developer’s transfer charge and DLD registration costs. Whether a resale is worthwhile depends on how prices have moved since launch and on demand for similar units. Our off-plan specialists can advise on resale timing and value. Browse off-plan projects.
You don’t legally need a UAE bank account to buy property in Dubai, and many overseas buyers pay by international transfer. In practice, having one makes the purchase easier, because payments at transfer are usually made by manager’s cheques from a UAE bank. Buyers without a local account can often arrange these payments through their conveyancer or the trustee office. If you’re taking a mortgage, you will need an account with the lending bank. Your advisor will explain the simplest payment route for your situation before you make an offer. See buying property in Dubai from abroad.
Yes, property in Dubai can be bought in a company’s name, but only certain types of company are accepted by the Dubai Land Department. These include UAE companies and companies registered in some free zones and approved offshore jurisdictions. The company will need to provide its licence, constitutional documents and board resolution, and foreign company documents usually have to be legalised. Buyers often choose a company for privacy, succession planning or holding several properties, but there are setup costs and possible tax considerations. Speak to a legal adviser about the right structure, and your USH advisor will coordinate the purchase with them.
Yes, some developers and sellers in Dubai accept cryptocurrency, usually through a licensed intermediary that converts it to dirhams before the transfer. The property is still registered with the Dubai Land Department in the normal way, with its price recorded in AED. You’ll need to show where your funds came from, as anti-money-laundering checks apply to every purchase. Not every seller or developer accepts crypto, so it’s best to say early if you plan to pay this way. Read our guide to buying Dubai property with Bitcoin.
If you own property in Dubai without a registered will, the distribution of your estate may be decided under UAE law rather than your wishes, and the process can take time for your family. To avoid this, many owners register a will, for example with the DIFC Wills Service Centre or the Dubai Courts, which sets out who inherits the property. Owning through a company or adding a joint owner can also affect what happens. Inheritance rules depend on your circumstances, so take advice from a qualified UAE lawyer. Your advisor can raise this at the start of your purchase, so the ownership structure fits your plans.
Yes, two or more people can buy a property together in Dubai, and all owners are named on the title deed with their ownership shares recorded. Each owner needs to provide their identity documents and sign the sale contract, either in person or through a power of attorney. If you’re taking a mortgage, the bank will assess you as joint applicants, which can increase how much you’re able to borrow. It’s worth agreeing the ownership shares and what happens if one owner later wants to sell before you buy. Ask your advisor to set up the joint purchase correctly from the start. See how buying works with USH.
Tell Us What You're Looking For
Share your budget, area and timeline, and a buying advisor will call you back.
- 200+
- Awards from top developers
- $10B
- Transaction value
- RERA
- Regulated brokerage
Written by USH Editorial TeamUpdated